
 Log In× Close


September 23, 2026
As the leaves turn brown and the year winds down, it’s easy to get caught up in holiday planning and family gatherings. However, there is another important date fast approaching: December 31st.
It’s important for taxpayers to be proactive with their finances before the clock strikes midnight. Navigating your 2026 taxes may require a fresh playbook, given certain provisions finalized under the One Big Beautiful Bill Act (OBBBA).
Here are some year-end tax moves you can consider making before the end of 2026.
A simple way to drop your adjusted gross income (AGI) is by fully funding your tax-advantaged accounts. Every dollar that goes into these accounts is a dollar the IRS can’t touch this year.
Introduced as part of the OBBBA, Section 530A Accounts (colloquially known as Trump Accounts) offer a brand-new tax-deferred wealth-building tool for children who have not turned age 18 before the end of the calendar year.
Unlike traditional IRAs, children do not need earned income to qualify for these accounts. If you are looking to build long-term savings for your dependents, keep these year-end rules in mind:
While traditional IRAs allow you to contribute up until the April filing deadline, Section 530A Accounts operate on a strict calendar year basis. All 2026 contributions must be completed by December 31, 2026. If you haven't opened one yet, you must register by submitting IRS Form 4547.
 Optimize Your Philanthropy
Charitable giving is highly encouraged under the current federal tax code, making this time of the year a perfect time to do some good while doing well for your wallet.
Even if you plan to take the standard deduction, you may not be entirely locked out of charitable breaks. Non-itemizers can claim an above-the-line deduction for cash donations up to $1,000 ($2,000 for married couples filing jointly) directly on their tax returns.
Don't let your hard-earned money vanish! Unlike HSAs, healthcare FSAs generally operate under a strict "use-it-or-lose-it" framework. The maximum contribution limit for voluntary salary reductions is capped at $3,400.
While some employer plans offer a small grace period or a carryover option of up to $680 into next year, many require you to exhaust the account by December 31st. Take time to check your balance. If you have remaining funds, schedule overdue medical appointments, update your prescription eyewear, or even consider stocking up on eligible over-the-counter medical supplies.
Tax planning is not a task meant for April, it’s something you should be thinking about throughout the year. Schedule an hour to pull your year-to-date pay stubs, thoroughly review all of your investment accounts, and estimate your 2026 income. A few deliberate shifts over the next few months can leave you with a significantly lower tax liability and a much healthier financial start to 2027.
For tax related matters, it’s always recommended to consult with your tax advisor regarding your specific situation.
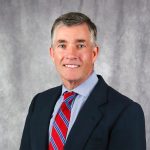 John McDonald is a Commercial Lender and Certified Public Accountant. He joined the New Tripoli Bank team in 2026. He has degrees in Business Administration, Management, and Taxation, and has worked with the IRS. He is also a veteran and has been part of the Weisenberg Township community for over twenty years, where he currently lives with his family.
 Log into Online Banking